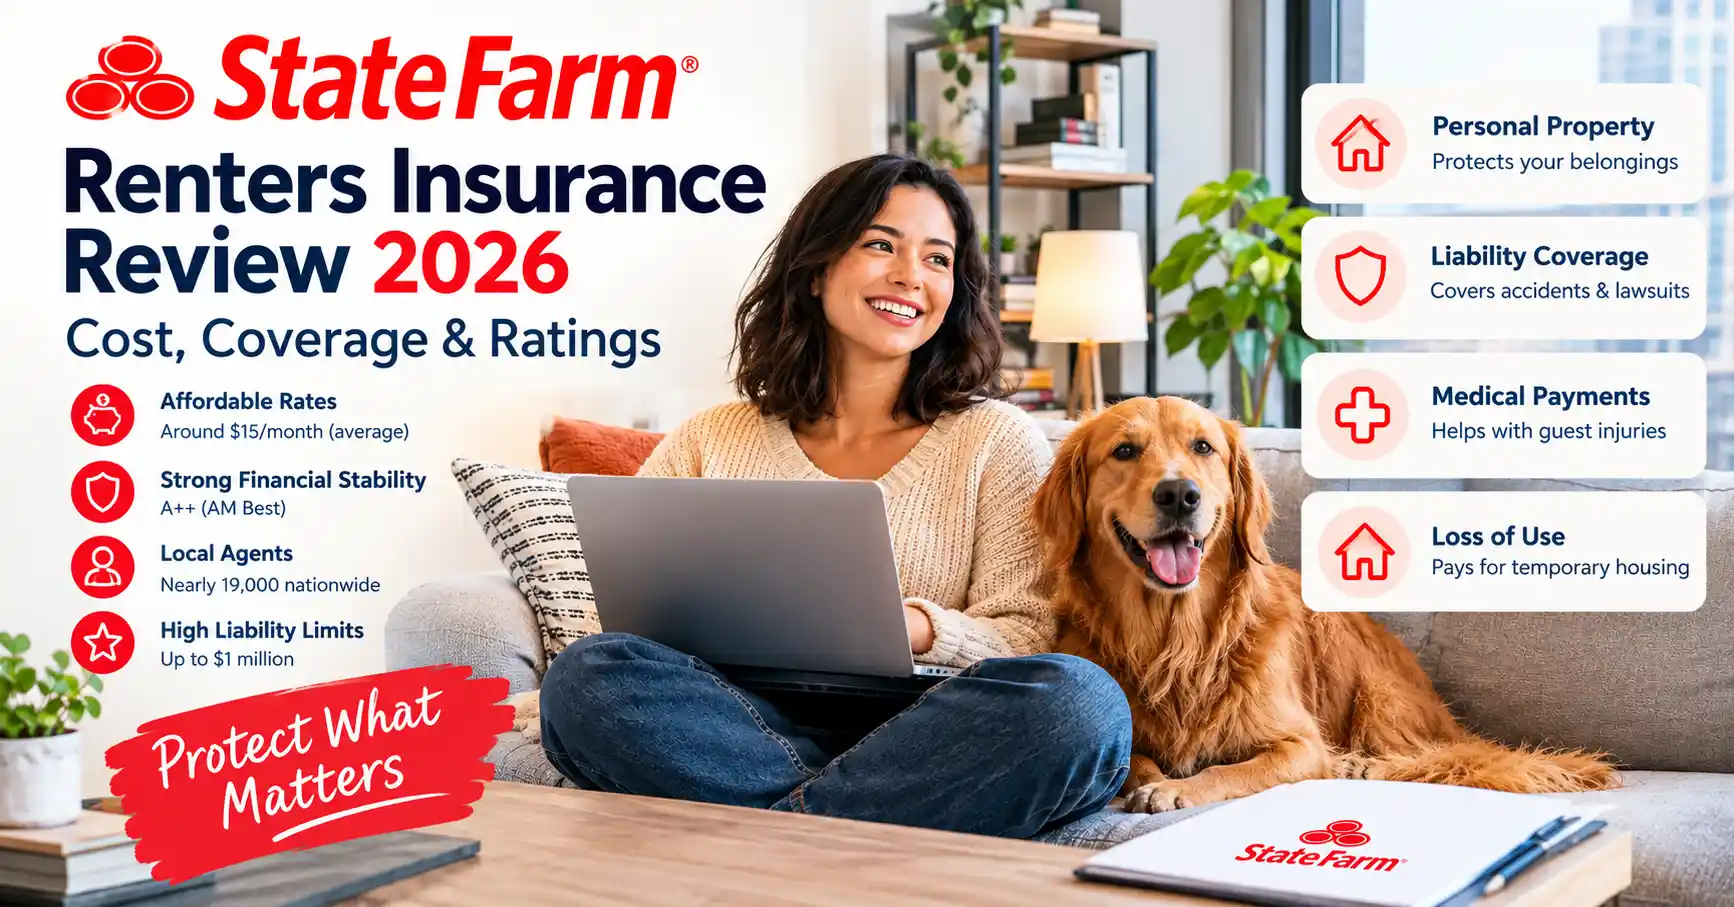
If you are searching for reliable renters insurance, State Farm is likely already on your radar as a top contender. Averaging roughly $15 a month for standard coverage, it delivers some of the most affordable and financially stable protection in the United States today. Backed by an exceptional A++ rating from AM Best and supported by a massive nationwide network of local agents, State Farm stands out as a rock-solid choice for tenants. This is especially true if you already use them for your auto insurance, as you can score a generous bundling discount. Beyond basic property coverage, their policies include essential liability and medical payments.
Key Takeaways
- Wallet-Friendly: At roughly $15 to $20 a month, policies fall below the national average.
- Guaranteed Payouts: Their A++ financial rating means they actually have the cash to pay out claims when disaster strikes.
- Real Human Support: You get access to nearly 19,000 local agents across the US.
- High Liability Limits: You can bump your personal liability protection up to $1 million.
- Fewer Bells & Whistles: You won’t find niche add-ons here, like the specialized pet damage riders offered by some digital-first competitors.
Pros and Cons of State Farm Renters Insurance
| Pros | Cons |
| + Cheaper-than-average monthly rates | – Fewer discount options than competitors like Allstate |
| + Top-tier financial stability (AM Best A++) | – Slightly higher NAIC complaint index (1.04 to 1.35) |
| + Massive network of local, dedicated agents | – Not writing new policies in certain high-risk areas (like parts of California) |
| + Generous personal liability limits | – Base policies completely exclude flood and earthquake damage |
If you are evaluating whether this legacy carrier is the right fit for your living situation, here is a deeper dive into who benefits most from a State Farm renters policy, who might want to shop around, and exactly what the coverage entails.
Who Is State Farm Renters Insurance Best For?
State Farm hits the sweet spot for budget-conscious tenants, drivers looking to bundle their policies, and renters who still value shaking hands with a local agent. Rather than chasing the app-first trend of newer insurtech startups, this legacy carrier relies on its massive national footprint and highly competitive pricing to win over apartment dwellers and home renters alike.
Here is exactly who benefits most from a State Farm policy:
The Ideal Candidates
- The Serial Bundler: If you already have State Farm auto insurance, adding a renters policy is one of the easiest financial decisions you can make. The multi-policy discount is famously generous, sometimes bringing the effective cost of the renters coverage down to just a few dollars a month.
- The Budget-Conscious Renter: Averaging around $11 to $15 per month (roughly 39% below the national average), State Farm consistently ranks as one of the absolute cheapest options on the market for standard personal property and liability protection.
- The “Real Human” Seeker: Unlike digital-only competitors that route you to AI chatbots, State Farmoperates through a vast network of local, dedicated agents. If you want a professional to demystify your liability limits or advocate for you during a complex claim, this traditional model is a major asset.
- Tenants Rebuilding Their Credit: While many property insurers heavily penalize lower credit scores, State Farm is uniquely positioned for offering highly competitive rates to renters with poor credit profiles.
How Much Does It Actually Cost?
State Farm plays hardball on pricing. Based on industry averages and internal data, a typical policy runs about $15 a month (roughly $180 a year) for up to $35,000 in personal property coverage.
That said, your exact quote will fluctuate based on a few key factors:
Where You Live: ZIP codes with high crime rates or frequent severe weather will bump up your premium.
How Much Stuff You Have: Upping your personal property limit from $30,000 to $50,000 costs a bit more each month.
Your Deductible: If you agree to pay more out-of-pocket before insurance kicks in (say, a $1,000 deductible instead of $500), your monthly bill drops.
Your Insurance Score: Unless you live in a state that bans the practice (like California or Massachusetts), insurers use your credit-based insurance score to set your rate.
What Does State Farm Renters Insurance Cover?
State Farm’s standard policy checks all the major boxes a renter needs.
1. Personal Property Coverage
This pays to repair or replace your stuff—furniture, clothes, tech—if it’s ruined by a covered “peril” like fire, smoke, vandalism, or theft.
Real-world example: A burglar breaks in and steals your $1,200 MacBook. State Farm cuts you a check for the loss, minus your deductible. They also include “off-premises” coverage, meaning that same laptop is covered even if it’s stolen out of the trunk of your car.
2. Personal Liability Coverage
If someone gets hurt in your apartment, or you accidentally wreck someone else’s property, this covers your legal defense and settlement costs. Standard policies start at $100,000, but you can scale this up to $1,000,000.
Real-world example: Your dog bites a delivery driver in the hallway. Your liability coverage steps in to help pay the driver’s hospital bills and your legal fees if they decide to sue.
3. Medical Payments to Others
This handles minor medical bills (usually $1,000 to $10,000) for guests who get injured at your place, regardless of whose fault it is. Note: This is strictly for guests, not you or your roommates.
4. Loss of Use (Additional Living Expenses)
If a kitchen fire forces you out of your apartment, Loss of Use pays for your temporary life elsewhere. This covers hotel bills, takeout meals, and even pet boarding. State Farm stands out here by covering these extra costs for up to 24 months with no strict dollar cap.
What Isn’t Covered?
Knowing what your policy won’t pay for is just as crucial. A standard State Farm renters policy excludes:
Floods: A burst pipe in your bathroom is covered, but weather-related flooding requires a completely separate policy through the National Flood Insurance Program (NFIP).
Earthquakes: You’ll need a separate endorsement if you live in a seismic zone.
Your Roommate’s Stuff: Your policy protects your things. Roommates need to buy their own policies.
High-Value Luxury Goods: Expensive jewelry, art, and firearms have built-in sub-limits (usually maxing out around $1,500 to $2,500). If you want to protect a $10,000 engagement ring, you have to buy a specific “Personal Articles” rider.
How to Score Discounts
State Farm doesn’t overwhelm you with dozens of tiny discounts. Instead, they lean heavily into one massive money-saver: bundling.
The Multi-Line Bundle: If you insure your car with State Farm, adding renters insurance is a no-brainer. The multi-line discount can often drop your renters premium to just a few dollars a month.
Home Alert Protection: You’ll get a small rate cut if your apartment has smoke detectors, fire alarms, or a monitored security system.
State Farm renters insurance is one of the most affordable and financially stable options on the market, but its true value depends heavily on whether you already use them for auto insurance and how much you value a traditional, agent-led experience.
Here is a detailed breakdown of why it might—or might not—be worth it for you.
Why State Farm Renters Insurance is Worth It?
- Unbeatable Bundling Discounts: If you already have a State Farm auto policy, adding renters insurance is a no-brainer. The multi-policy discount is incredibly generous—often bringing the effective cost of your renters policy down to just a few dollars a month.
- Highly Competitive Standalone Rates: Even without a bundle, State Farm averages around $11 to $15 per month ($104 to $153 annually) for standard coverage. This consistently ranks roughly 26% to 39% below the national average, making it a top pick for budget-conscious tenants.
- Forgiving for Poor Credit: Many insurance companies heavily penalize renters with lower credit scores by jacking up their premiums. State Farm is unique in offering highly competitive rates even if your credit profile isn’t perfect.
- Unique Coverage Options: Beyond standard property and liability protection, State Farm offers an “inflation coverage” endorsement. This automatically adjusts your personal property limits to keep pace with the rising cost of replacing your belongings. They also offer optional add-ons for cyberattacks, identity restoration, and earthquake damage.
- Local Agent Network: Unlike digital-first startups, State Farm relies on a massive network of dedicated, local agents. If you value having a real human being to explain your liability limits or advocate for you during a complex claim, this is a major advantage.
Where State Farm Insurance Falls Short
- Fewer Standalone Discounts: While the bundling discount is massive, State Farm lacks the variety of smaller discounts offered by competitors (like paperless billing, auto-pay, or claims-free discounts).
- Mixed Claims Experience: While individual local agents are often highly rated, overarching corporate claims handling has drawn mixed reviews regarding speed, unexpected policy cancellations, and ease of resolution.
- Not for the App-Obsessed: If you want a fully digital, zero-human-interaction experience with under-five-minute signups and AI-driven instant claims, startups like Lemonade will feel much more modern.
Customer Service, Claims, and Industry Ratings
- Financial Strength: State Farm holds an A++ (Superior) rating from AM Best. You never have to worry about them going bankrupt after a major natural disaster.
- Customer Satisfaction: They consistently score above average in J.D. Power’s U.S. Home Insurance Studies.
- The Claims Process: Reviews here are mixed. While users love having a local agent to call, their NAIC complaint index sits slightly above the national average (meaning they get slightly more complaints than expected for a company their size).
- Filing a claim: You can do it through the State Farm app, online, over the phone, or by walking into your local agent’s office. (Pro tip: take a video walking through your apartment today so you have a home inventory ready if you ever need it.)
State Farm Insurance vs. The Competition
Here is how State Farm stacks up against other major US players:
| Feature | State Farm | Lemonade | USAA |
| Best For | Bundling with Auto | Tech-savvy minimalists | Military & their families |
| Avg. Monthly Cost | ~$15 | ~$12 – $15 | ~$18 |
| Flood/Earthquake | Separate policy needed | Separate policy needed | Included in base policy |
| Customer Service | Local Agents & Phone | AI-driven app experience | Phone-based |
(Note: USAA is strictly limited to active military, veterans, and eligible family members).
How to Get a Quote
- Go Online: Head to StateFarm.com, punch in your ZIP code, and answer a few quick questions about your building.
- Call an Agent: If you have high-value items, want to max out your liability, or need to bundle policies, finding a local agent on their site is the smartest move.
- Be Prepared: Know your exact address, what safety features your building has (like sprinklers or deadbolts), and a rough estimate of what your stuff is worth.
The Landlord Myth: Doesn’t My Building’s Insurance Cover Me?
One of the most dangerous misconceptions among renters is assuming their landlord’s insurance protects them. It does not.
Your landlord’s policy only covers the physical structure of the building—the roof, the walls, and the plumbing. If a pipe bursts and ruins the drywall, the landlord’s insurance pays to fix the wall. But if that same water destroys your custom PC, your mattress, and your vintage sneaker collection, the landlord’s policy pays you absolutely zero. Renters insurance is the only way to protect your personal financial assets inside the unit.
Replacement Cost vs. Actual Cash Value (The Payout Catch)
When you buy a policy, you need to know exactly how State Farm will calculate the value of your ruined items. There are two ways this is handled:
- Actual Cash Value (ACV): The insurance company pays you what the item was worth at the time it was destroyed, factoring in depreciation. If your 5-year-old TV is stolen, ACV might only pay you $150, because that is what a used TV is worth today.
- Replacement Cost Value (RCV): The insurance company pays what it costs to buy a brand-new version of that item today at Target or Best Buy.
- Pro Tip: Always double-check with your State Farm agent to ensure your policy includes Replacement Cost coverage. It costs slightly more per month, but it prevents you from receiving a shockingly low payout after a disaster.
Decoding Your Deductible
Your deductible is the amount of money you agree to pay out of your own pocket before State Farm steps in to cover the rest.
- How it works: If you have a $500 deductible and a thief steals $2,000 worth of electronics from your apartment, State Farm will write you a check for $1,500.
- How it impacts your bill: There is an inverse relationship between deductibles and premiums. If you choose a high deductible (like $1,000), your monthly bill will be cheaper. If you want a low deductible (like $250), your monthly bill goes up. Most US renters find a $500 deductible to be the best middle ground.
Renting with Pets: State Farm’s Famous Dog Policy
Finding renters insurance can be a nightmare if you own a “restricted breed” like a Pitbull, Rottweiler, or German Shepherd, as many major US insurers will outright deny you coverage.
State Farm is famously breed-inclusive. They do not ask what breed of dog you own when you apply for a quote. Instead, they look at your dog’s individual bite history. As long as your dog does not have a documented history of aggression, State Farm will extend personal liability coverage to you. For pet owners, this is one of State Farm’s biggest competitive advantages.
How to Actually File a Claim (Step-by-Step)
If the worst happens, here is exactly what you need to do to get paid by State Farm without delays:
- Ensure Safety & Call the Police: If you are the victim of a theft or vandalism, call the police immediately. State Farm will require a police report number to process a theft claim.
- Document the Damage: Take extensive photos and videos of the damage before you clean anything up.
- Prevent Further Loss: If a window is broken, board it up so rain doesn’t ruin more items. State Farm requires you to mitigate further damage.
- File the Claim: Open the State Farm mobile app or call 1-800-SF-CLAIM. Upload your photos, the police report, and any receipts you have for the damaged items.
- Keep Your Receipts: If you are forced to stay in a hotel under your Loss of Use coverage, save every single hotel and restaurant receipt. You will need to submit these to your claims adjuster for reimbursement.
Final Verdict
For most US renters, State Farm is a top-tier choice. For about $15 a month, you get generous coverage, high liability limits, and the peace of mind that comes from a financially bulletproof company. If you already have a State Farm auto policy, the bundle discount makes it an absolute steal.
If you want a 100% digital, app-first experience or need niche add-ons, you might prefer Lemonade. But for traditional, reliable coverage, State Farm is hard to beat.
Frequently Asked Questions
Does State Farm renters insurance cover theft from a car? Yes. Your policy includes “off-premises” coverage. So, if your laptop gets swiped from your car while you’re grabbing groceries, State Farm covers the loss (after you pay your deductible).
If my apartment is unlivable, will they pay for my hotel? Yes. If a covered peril (like a fire) forces you out, State Farm’s Loss of Use coverage pays for your hotel, extra food costs, and temporary housing for up to 24 months.
How much personal property coverage do I actually need? People always underestimate this. Walk through your place and ask: What would it cost to buy all of this brand new today? Between clothes, furniture, a TV, and a laptop, most renters need between $20,000 and $35,000 in coverage.
Does my policy cover my roommate? No. Your policy covers you. Unless you are legally married, your roommate needs to buy their own separate renters insurance.
Does State Farm cover dog bites? Yes. The personal liability portion of your policy covers the medical bills and legal fees if your dog bites someone. Just make sure you tell State Farm you have a dog when you sign up—some states allow insurers to exclude certain breeds with a history of biting.
Keep Learning:
Pharmacy Insurance Explained: 10 Powerful Ways to Understand Your Drug Coverage
1 thought on “State Farm Renters Insurance Review 2026: Powerful Benefits, Costs & Drawbacks”